
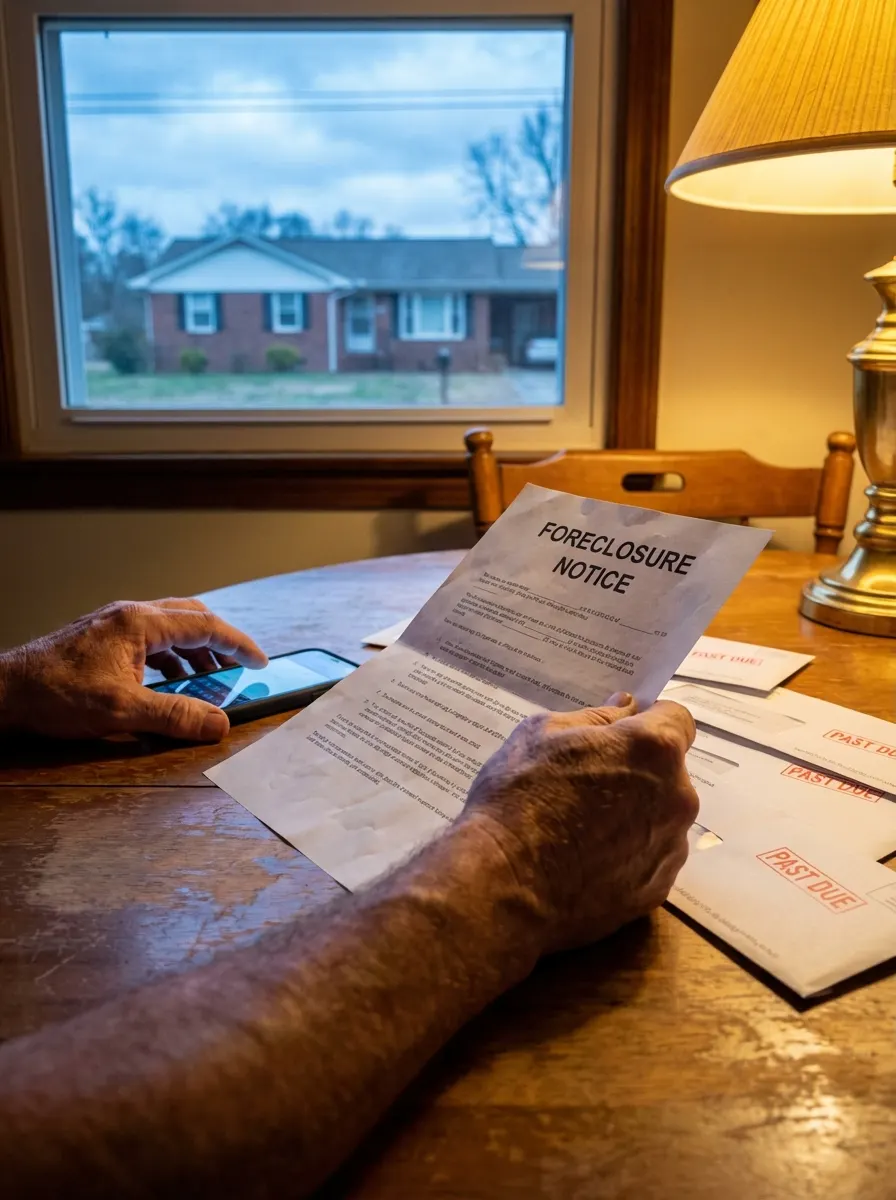
There is a certified letter on your counter. You know what it is: a substitute trustee has filed a notice of hearing with the Guilford County Clerk of Superior Court, and there is a date on it.
Here is what nobody tells Greensboro homeowners early enough. You still own the house. You can still sell it. The foreclosure only takes your equity if you let the auction happen first.
I am Ryan Smith. I founded Cinch Home Buyers in Cary in 2021 and we have closed 250+ properties across North Carolina, many from owners somewhere on this clock. I am not an attorney and not a real estate agent. What follows is general information about how the process works, plus what a cash sale can and cannot do. For your case, talk to a North Carolina real estate attorney.
The Guilford County Foreclosure Timeline
Almost every residential foreclosure in Greensboro is a power-of-sale foreclosure. The deed of trust you signed at closing gave a trustee the contractual power to sell if you default — but the trustee cannot do it alone. A power-of-sale foreclosure in North Carolina cannot proceed unless a court authorizes it after a hearing, and that authority sits with the clerk of superior court in the county where the property is. For a Greensboro house, that is the Guilford County Clerk of Superior Court.
Step 1 — The 45-day pre-foreclosure notice
Under N.C.G.S. § 45-102, the servicer must mail a written pre-foreclosure notice to the borrower's last known address at least 45 days before filing the notice of hearing. It itemizes the past-due amounts and lists contacts for the servicer, HUD-approved counseling agencies, and the State Home Foreclosure Prevention Project run by the NC Housing Finance Agency. Most people throw this letter away. Do not — it is the cleanest early snapshot of what you owe to reinstate.
Step 2 — The notice of hearing
The trustee files a notice of hearing with the Guilford County Clerk of Superior Court as a special proceeding. It states the date, time, and place, and must be served not less than 10 days before the hearing.
Step 3 — The clerk's hearing
This is not a trial about whether foreclosure is fair. The clerk decides four narrow questions: whether there is a valid debt and the party foreclosing holds it, whether you are in default, whether the instrument gives a right to foreclose, and whether proper notice went out. All four, and the sale is authorized. That ruling can be appealed within 10 days and heard de novo — but whether an appeal makes sense is an attorney conversation, not a cash-buyer one.
Step 4 — The sale, then the upset bid window
The auction is not the end. Once the sale is conducted there is a 10-day upset bid period during which anyone can file a higher bid with the clerk. Under N.C.G.S. § 45-21.27, an upset bid must exceed the reported sale price or last upset bid by at least five percent, with a minimum increase of $750 — and each new upset bid starts a fresh 10-day clock.
So a sale can bounce for weeks. That is not a reason to relax — it means that once the gavel drops, control of the outcome leaves your hands entirely.
Where You Are on the Clock Right Now
Find yourself in this list. It determines what is realistic.
- Behind, nothing filed. The strongest position you will ever be in, and the one people waste. Every exit is open and nothing is public.
- Pre-foreclosure letter received. The countdown runs but the courthouse is not involved. Six or seven weeks covers almost any exit, including a conventional listing.
- Notice of hearing served. A public proceeding with a date attached. Retail listing gets risky — a financed buyer needs an appraisal, an underwriter, and 30 to 45 days you may not have.
- Sale authorized, date posted. Days matter. A cash closing can still beat the date, but the payoff quote has to be in hand. Call the same day, not next week.
- Already sold at auction. Your options are legal ones now, not sales ones. Call an attorney immediately.
Ask your servicer, in writing, for a reinstatement quote (what it costs to bring the loan current today) and a payoff quote (what it costs to satisfy the loan in full, good through a specific date). Every decision below — modify, file, sell, or walk — is guesswork until you have both numbers. Any legitimate buyer will need the payoff quote anyway.
Selling vs. Loan Modification vs. Chapter 13
These get thrown around as if they are interchangeable. They are not.
Loan modification
A modification changes the loan's terms — rate, term, or how arrears are handled — so the payment becomes affordable again. Right answer when the hardship is over and your income can support a house you want to keep; wrong answer when the math never worked. Servicers approve at their discretion, review takes time, and applying does not by itself stop a scheduled sale. A HUD-approved counselor can help assemble the package at no cost.
Chapter 13 bankruptcy
Chapter 13 is a court-supervised repayment plan. Filing triggers an automatic stay that generally halts collection activity, including a scheduled foreclosure sale, while the case is pending, and the plan is designed to let a debtor cure mortgage arrears over time while staying current going forward. It also carries real costs, a multi-year commitment, and consequences beyond this house.
Plainly: I am a cash home buyer, not a bankruptcy attorney, and whether Chapter 13 fits your finances is not mine to answer. Talk to a licensed North Carolina bankruptcy attorney before the hearing date, not after.
Selling before the sale
Selling is the only option here that turns the house into cash instead of a payment you still owe. The attorney pays the loan off at closing, the foreclosure is dismissed, and whatever is left after payoff and liens is yours. The trade-off is real: a cash offer is below what a repaired house lists for, because we take the repairs, the carrying costs, and the risk.
For the statewide view, read how to stop foreclosure in North Carolina and how long the NC foreclosure timeline runs.
| Factor | Loan Modification | Chapter 13 | Sell Before the Sale |
|---|---|---|---|
| You keep the house | Yes, if approved | Yes, if the plan holds | No |
| Who decides | Your servicer | Bankruptcy court | You |
| Professional needed | HUD counselor | Bankruptcy attorney | NC closing attorney |
| Out-of-pocket cost | Varies | Filing and attorney fees | $0 with a cash buyer |
| Typical timeline | Weeks to months | 3-5 year plan | As little as 7 days |
The auction does not care what your house is worth. It cares what the debt is. That gap — between market value and payoff — is your equity, and it is the thing a foreclosure sale is least designed to protect.
What a 7-Day Close Actually Looks Like
People hear "close in as little as 7 days" and assume it is marketing. It is real, but only when a few things line up.
Day 1. Call (919) 751-6768 with the address, rough condition, and the sale date if one is posted. Mention the foreclosure immediately — a buyer who finds out on day five costs you days you do not have. Request the payoff quote from your servicer the same day; it is usually the long pole in the tent.
Day 1-3. We look at the house, pull comparable sales, and hand you a written offer with the reasoning behind the number. Signed contract goes straight to the closing attorney, who opens title.
Day 3-6. Title work, where deals actually slow down. A second mortgage, a judgment, back taxes, a contractor's or IRS lien, or an unresolved estate on the deed all have to be cleared or paid at closing. None are deal-killers by themselves — they are just time, which is why you call early.
Day 7. You sign, the attorney disburses, the loan is paid off, the foreclosure is dismissed, and anything left is yours. Where 7 days breaks: a servicer that takes two weeks to issue a payoff, heirs nobody has located, or a title defect needing curative work — and we tell you which before you sign, not after.
Greensboro Neighborhoods We Buy In
Greensboro is not one market, and the right move on Elm Street is not the right move off Randleman Road. Three areas we get called about constantly:
Glenwood
Southwest of downtown next to UNCG, Glenwood is a dense grid of early-twentieth-century bungalows and mill-era cottages on small lots. Many have been rentals for decades: original wiring, aging roofs, deferred maintenance an appraiser flags on sight. A house that will not appraise cleanly, plus a foreclosure clock, is exactly where a cash sale beats a listing.
Lindley Park
West of downtown near Wesley Long, Lindley Park is one of Greensboro's more desirable older neighborhoods — mature trees, walkable, well-kept 1920s-1950s stock. Values are strong enough that owners are often surprised how much equity sits in a house they assumed was underwater. Run the payoff number first.
East Greensboro
East of downtown, around NC A&T and along the Bessemer and East Market corridors, the housing stock is older and the maintenance burden heavier. It is also where we see the most inherited property — a parent passes, the mortgage keeps running, the heirs live out of state, and by the time anyone acts there is a foreclosure filing and an estate nobody opened. Both are solvable, but the estate side takes an attorney and time, which is what a posted sale date does not give you.
For the full local picture, see our page on selling your house fast in Greensboro, NC.
Keeping the Equity the Auction Would Take
A foreclosure auction is not a market. It is a legal mechanism for satisfying a debt. The opening bid is typically tied to what the lender is owed, and the pool of bidders on a courthouse step at eleven in the morning is a fraction of the pool that would look at your house online. If the property brings more than the debt plus the costs of sale there can be a surplus, and surplus belongs to the borrower — but "can be" is doing heavy lifting there, and claiming surplus funds is a question for an attorney.
A cash sale before that date pays the loan in full at closing and hands you whatever is left. No bidding, no gamble, no chain of upset bids to wait out. A completed foreclosure also sits on your credit as public record for years; a sale that pays the loan off is just a sale.
I will not tell you selling is always the answer. If you can reinstate, keep the house. If a modification puts you back on your feet, take it. If an attorney says Chapter 13 fits, do that. Selling is right when the payment was never going to be affordable again and the equity is worth protecting — which describes more Greensboro owners than most people expect.
Read further: selling before the foreclosure auction in NC, how to stop foreclosure in North Carolina, and the same timeline in Charlotte.
Frequently Asked Questions
Yes. You own the property and can sell it up until the foreclosure sale is confirmed. The proceeds pay off the loan through your closing attorney, and the foreclosure is dismissed. The practical limit is time: your closing has to fund before the sale, so ask your servicer for a written payoff quote as soon as possible.
Under N.C.G.S. § 45-102 the servicer must mail a pre-foreclosure notice at least 45 days before filing the notice of hearing. The notice of hearing must then be served at least 10 days before the clerk's hearing. After the sale there is a 10-day upset bid period, and each new upset bid restarts another 10 days. Real cases vary widely depending on continuances and bidding.
After a foreclosure sale, anyone may file an upset bid with the clerk during the 10-day period. Under N.C.G.S. § 45-21.27 the upset bid must exceed the last bid by at least five percent, with a minimum increase of $750. Each upset bid starts a new 10-day period, so a sale is not final on auction day.
Only if the final bid exceeds what is owed plus the costs of the sale. Foreclosure auctions are built to satisfy the debt, not to find market value, so surplus is far from guaranteed. Selling before the sale is the more reliable way to protect equity. Ask an NC real estate attorney how surplus funds are handled in your specific case.
A bankruptcy filing triggers an automatic stay that generally halts collection activity, including a scheduled foreclosure sale, while the case is pending. Chapter 13 is a court-supervised repayment plan that can allow arrears to be cured over time. Eligibility, cost, and outcome depend entirely on your finances, so this is a question for a licensed bankruptcy attorney, not a home buyer.